Earlier this week, ICEYE, a spinout from Aalto University, made a €2.05 billion cash offer for Avio, the Italian company that has the Vega launcher. The very next day, the European Spinouts Report 2026, published with Atlantic, MITO Technology, Forward.one, and AlbionVC, highlighted the sector’s strength.
The total value of deep tech and life sciences spinouts is now at $492 billion: companies employ over 220,000 people across more than 9,300 startups and are expected to raise a record $16.1 billion this year, a 44% increase on 2025.
The report was launched at Slush in Helsinki, which Tech Funding News attends this year. Since 2019, spinouts have accounted for 46% of new deep tech and life sciences startups, and 14 of them have now become unicorns.
Defence and space sectors are driving growth
Defence spinouts raised more in 2026 than they did in the combined years 2020 to 2025. Nuclear was in the same position as in the previous six years. Three spinouts made the top five most valuable this year.
Quantum Systems, spun out of Bundeswehr University Munich, raised $1.2 billion at an $8 billion valuation, while Tekever, originating from the University of Lisbon, raised $580 million at a $ 6.4 billion valuation after being awarded a UK contract worth up to £400 million.
ICEYE raised €450 million at a valuation of over €10 billion, up from €2.4 billion just six months prior and reported over €250 million in revenue for 2025. Isar Aerospace, a TU Munich spinout, closed a €270 million round, and Proxima Fusion from the Max Planck Institute secured €411 million.
The AI chip and quantum are both progressing. Fractile, founded by Oxford’s Walter Goodwin, hit a $7 billion valuation following a $720 million funding round, despite still not having a production chip. OQC raised £260 million, and OMass is also one of the largest UK funding rounds.
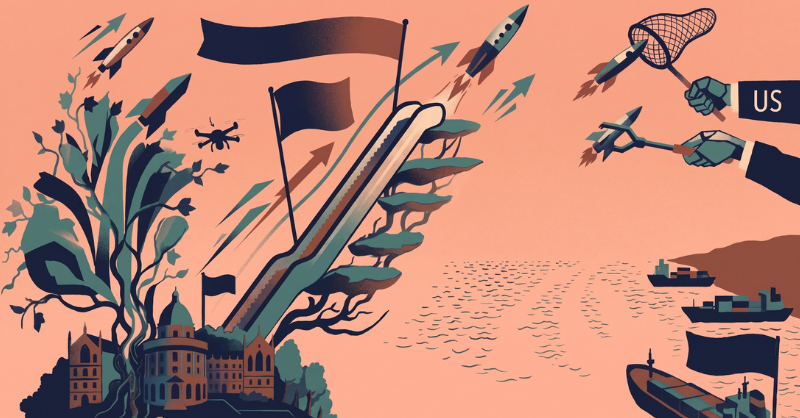
Europe builds while the US invests
89% of early-stage funding comes from Europe, while 44% of late-stage funding comes from outside Europe, down from 65% in 2021 and 2022. Of the non-European investors, Lightspeed led the most $100M+ rounds, and NVIDIA was involved in five. The most active investors in the rounds were EIC Fund, Forbion, Balderton and Bullhound.
US buyers are taking a bigger slice of the exit pie, having taken over $33 billion in exit value since 2020. Europe have done more exits by count, but those accounted for just about a quarter of the total value.
Of the eight $1B+ exits, six were Europe-headquartered spinouts. The two biggest were Eli Lilly’s $3.3 billion acquisition of a CNRS and MIT spinout and Gilead’s $3.2 billion purchase of an LMU and Leibniz spinout. The European exits included Pasqal and IQM going public on Nasdaq via SPACs, Silex’s $1.1 billion exit and SAP’s $1.1 billion acquisition of Prior Labs, per Dealroom.
Riemer Smink, general Partner at Forward.one, said, “The next category-defining companies are being built in Europe’s labs. Our job is to make sure they grow here. Breakthrough technology rarely comes from improving what already exists. It comes from research that opens up something entirely new, and much of that research happens in Europe’s universities.”
David Grimm, partner at AlbionVC, added, “Europe has world-class technical talent, an increasingly strong early-stage investment ecosystem and a growing number of ambitious academics turned founders building companies around frontier technologies. The challenge is getting these businesses out of universities faster, then ensuring they have access to the deep pools of capital needed to support $100m+ rounds and build the next generation of global technology leaders in Europe.”
Terms are changing, with Oxford in the lead
Oxford tops the university ranking, followed by Cambridge, ETH Zurich, EPFL and TU Munich. UCL, Imperial, Aalto, Bristol and DTU complete the top 10. The UK leads in total value, with Germany and France next, while Switzerland leads per capita.
Europe is still two to three times behind the US in unicorns and funding and 13 times behind in value.
Terms are increasingly standardised. The average UK university equity stake has fallen from 25% in 2023 to 16% in 2025. Denmark introduced standard contracts in January with a 1-6% royalty and an optional 3-5% equity stake. Germany’s framework suggests 5-15% equity, and Dutch Express Terms suggest 2-4%. An EU blueprint is due by the end of 2026, and TFN have reported on the equity issue.
Prof Massimiliano Granieri, managing director at MITO Technology, noted, “With 14 new unicorns and $1B+ exits from European spinouts in 2026 alone, the case is made: research turned into companies creates sustainable and lasting value. Universities and public research institutions should treat spinout creation and growth as a core metric, one that attracts the best students, talent and funding as much as publications and a perspective of academic career do.”
Christophe Maire, founder and managing partner at Atlantic, concluded: “Europe’s scientific depth has always been world-class; what has improved dramatically is the determination of founders to commercialise it, and an ecosystem increasingly ready to support them. This year’s data shows this clearly: a growing number of researchers are turning scientific breakthroughs into some of Europe’s most valuable companies.”
Europe has proved it can turn world-class science into valuable companies. Now it must make it easier for those companies to scale, secure late-stage capital and build lasting industrial strength at home. The next chapter of Europe’s spinout story will be measured not just by the value created, but by how much of that value remains in Europe.