- NinjaOne has raised more than $400M at a $12.3 billion valuation, with Wellington Management, Teachers’ Venture Growth, Sequoia Capital, and ICONIQ participating.
- The Austin-based unified endpoint management platform serves more than 24,000 customers, including Nvidia, Lyft, HelloFresh, and Porsche, managing millions of devices for IT teams and managed service providers globally.
- The capital will accelerate R&D into autonomous endpoint management and vulnerability remediation, and follows the company’s completed $262 million acquisition of Dropsuite.
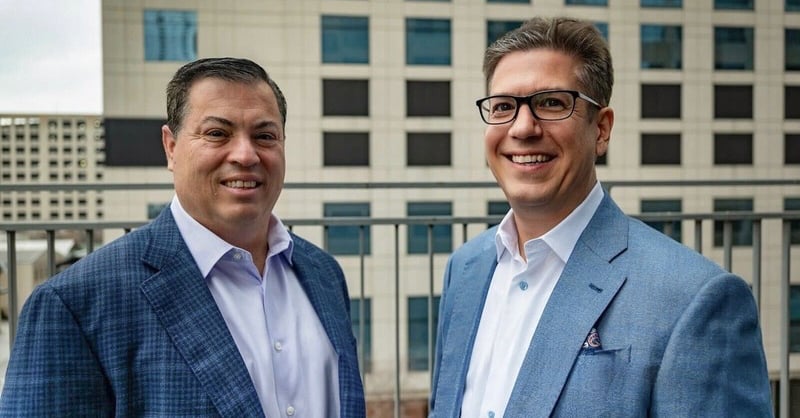
In February 2024, NinjaOne, founded in 2013 by Sal Sferlazza and Christopher Matarese, was valued at $1.9 billion. A year later, it raised $500 million at a $5 billion valuation.
Now it has closed a further $400 million-plus, bringing the total to $12.3 billion, a more than sixfold increase in valuation in eighteen months. Wellington Management, Teachers’ Venture Growth, Sequoia Capital, ICONIQ, and other investors participated in the round.
The growing crisis of endpoint sprawl
Modern organisations face a rapidly expanding operational problem: managing, monitoring, and securing a growing fleet of laptops, servers, mobile devices, and cloud endpoints across global, hybrid workforces.
For internal IT teams and Managed Service Providers, keeping software patched, securing data, and executing remote troubleshooting typically requires a fragmented set of disconnected legacy tools from multiple vendors.
NinjaOne was built to centralise that infrastructure into a single platform. The cloud-native system unifies remote monitoring, automated patch management, endpoint security, and data backup, allowing IT teams and MSPs to manage everything from one dashboard without switching between tools.
Today, the platform manages millions of endpoints for more than 24,000 clients globally, including Nvidia, Lyft, HelloFresh, Porsche, Cintas, and Vimeo.
The company has no debt and remains founder-led and founder-controlled. Sferlazza and Matarese retain majority equity, majority board control, and majority voting power.
A portion of the new capital follows through on NinjaOne’s completed $262 million acquisition of Dropsuite, a cloud backup and data protection platform. The rest is earmarked for R&D into autonomous endpoint management, automated vulnerability remediation, and AI-assisted helpdesk features.
“In moments like this, the market rewards companies that deliver real, operational value. NinjaOne has built its platform around the premise of unifying IT to simplify work, and is integrating AI in a way that strengthens, not complicates, that foundation,” says Derek Zanutto, General Partner at CapitalG.
The competition and broader outlook
NinjaOne operates at the intersection of IT automation and cybersecurity, consolidating rapidly around a handful of platforms.
Atera, which raised $77M in a 2022 Series C, differentiates through an integrated helpdesk, PSA, and flat per-technician pricing. At the same time, JumpCloud, which raised $159M at a $2.56 billion valuation in 2022, approaches the problem from an identity and access management angle, controlling user authentication and device access rather than relying on heavy-duty patching and remote operations. Kaseya and N-able are the two legacy incumbents most directly competing for the MSP segment.
NinjaOne’s differentiation is operational depth combined with ease of use: real-time remote monitoring, granular scripting, and rapid, policy-based patch deployment at enterprise scale, without the complexity imposed by legacy platforms.
The question for NinjaOne at $12.3 billion is whether the company can build the AI-native capabilities required to defend its position as larger players, including Microsoft and Google, continue to expand their own endpoint and identity offerings into the same space.