Most software categories grow because a product gets better or cheaper. Occasionally, one grows because a rule changes and a free option disappears.
US business messaging has spent two years demonstrating the second pattern. Carriers introduced a registration requirement, closed the routes that avoided it, and a large population of small businesses that had never paid for messaging suddenly had to.
The interesting part for anyone watching this space is that the displaced demand was invisible beforehand. It generated no revenue, appeared in no forecast, and belonged to no vendor.
What actually changed
Two things happened in sequence, and the second is what made the first enforceable.
Registration became mandatory
Application-to-person messaging in the US now requires senders to register through The Campaign Registry under a standard called 10DLC. A business registers its identity and its use case before carriers will deliver its messages reliably.
The driver was spam volume. Unauthenticated routes gave carriers nothing to filter on, and phishing traffic had become unmanageable.
The free routes closed.
Carriers simultaneously withdrew the email-to-SMS gateways that had operated since before smartphones. AT&T closed its service in June 2025, T-Mobile’s failed in December 2024, and Verizon’s is scheduled to end by March 2027.
Those gateways were the main way senders bypassed registration. Closing them was the enforcement step rather than a separate decision.
The demand nobody had counted
What makes this shift unusual is that the affected businesses were not previously customers of anything. They now face the same 10DLC compliance requirements as enterprise senders, despite having no prior relationship with any messaging vendor.
No vendor, no revenue, no data
The free gateways required no account and no contract. A dental practice typed an address into its scheduling software, and it worked. There was no relationship to the survey and no spending to measure.
That volume was substantial. Appointment reminders, billing alerts, delivery notifications, and system alerts were flowing at scale through a channel that produced no market data at all. Estimating it now requires working backwards from registration activity rather than forwards from historical spend.
Operational messaging, not marketing
Nearly all of it was one-to-one and transactional, which is the least visible category of business messaging. It attracts none of the attention that promotional campaigns do.
The distinction carries no regulatory weight, however. A single appointment confirmation faces identical registration requirements to a promotional broadcast reaching fifty thousand subscribers, which is what pulled the operational segment into a paid market it had never participated in.
Where the demand landed
The displaced volume did not distribute evenly across the provider landscape.
Enterprise API providers gained scale, not new positioning
CPaaS players already dominated registered traffic. The shift widened their addressable base but did not change their model, which still assumes developer resources most of these businesses do not have.
Mid-market platforms gained customers with a fit problem.
Dashboard-based SMS platforms absorbed businesses that needed reliable delivery without campaign tooling. Many now pay for segmentation, scheduling, and analytics they never use.
Pricing built around campaign volume also sits awkwardly with a practice sending forty reminders a week. That mismatch is worth watching in renewal data, since acquisition driven by necessity tends to retain worse than acquisition driven by preference.
The simplest tier grew fastest relative to its size.
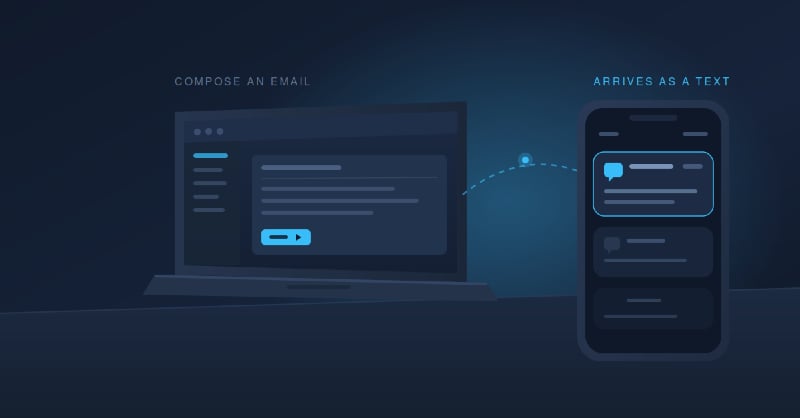
Services that replicate the old gateway behavior, accepting an email and delivering a text through a registered number, captured the segment that wanted the function without the platform. The migration path is a configuration change rather than a procurement exercise, which matters for businesses without technical staff.
According to Grand View Research, application-to-person messaging continues to expand with alerting and notification use cases among the primary drivers, which is precisely where this displaced volume sits.
Which verticals moved first?
Migration urgency tracked the cost of a failed message rather than company size.
Healthcare
Appointment reminders were the heaviest single use of free gateways. A missed appointment carries a direct revenue cost, so practices moved quickly once reminders stopped arriving. The feedback loop here was days rather than months.
Financial services
Payment reminders and fraud alerts carry regulatory sensitivity. This segment migrated earliest, since unregistered sending became untenable the moment registration existed.
Field services and IT operations
- Technician dispatch and arrival notifications.
- Monitoring alerts routed to on-call staff.
IT operations was the slowest to notice. Because failed messages returned no errors, many organisations discovered the problem only during incident reviews months later. Monitoring stacks reported healthy while delivering nothing, which is the worst available failure mode for an alerting system.
What to watch next
Three indicators say more about this market than message volume does.
Registration counts, not send volume
The messages already existed. New 10DLC registrations by small and mid-size businesses is the truer measure of how far migration has progressed.
The March 2027 deadline
Verizon’s remaining gateway has a fixed end date. A final tranche of displaced volume should surface as it approaches, though delivery is already close to zero.
Churn in the mid-market
Businesses paying campaign pricing for operational messaging represent the least stable cohort in this market. Where they move next will determine how the tiers settle.
A market created by rule, not by product
The clearest way to read the past two years is that demand did not increase. It became visible.
Traffic that had run free for over a decade moved into paid services because the free path closed, which means apparent growth partly reflects newly measurable activity rather than new activity.
That distinction matters for anyone sizing this opportunity. Registration data gives a cleaner signal than revenue growth and will continue to until the migration finishes.
It also sets a precedent worth noting. A compliance requirement converted an untracked category into a measurable one, without any product cycle or demand shift driving it. Similar mechanisms exist in other regulated communication channels, and they tend to move quickly once enforcement begins.