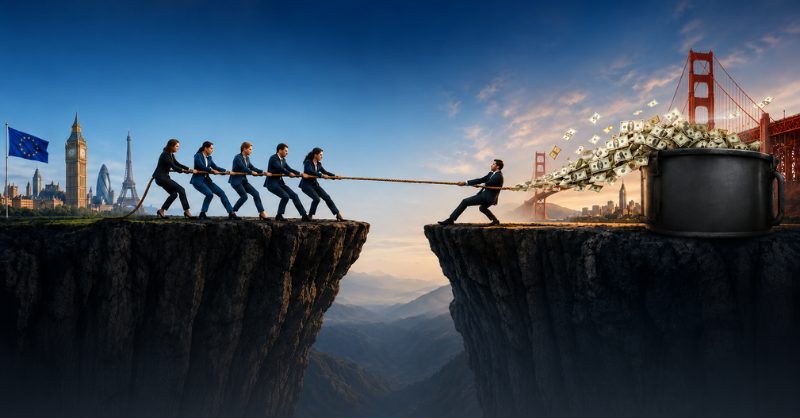
European VC funds have outperformed North American peers over 10 and 15-year horizons on an average-fund-versus-average-fund basis, delivering net IRRs of 16.59% and 17.06% respectively, according to Invest Europe’s 2025 benchmark report. Active European VC funds are running at a 2.14x TVPI and 13.48% IRR, with eight out of ten currently in profit.
In early 2026, Andreessen Horowitz closed a $15 billion fund, roughly 18% of all venture capital dollars allocated in the US in 2025. Thrive Capital raised $10 billion for its largest-ever vehicle, heavily oversubscribed. Sequoia, with Apple, Google, YouTube, and Stripe on its scorecard, remains the firm every LP in the world wants a piece of. The gravitational pull of American venture capital is so strong that it barely requires justification.
But a significant body of evidence now suggests the justification no longer holds.
New data from Invest Europe’s Performance Benchmark Report 2025, independently authored by Cyril Demaria and based on Cambridge Associates data, shows that the average European VC fund has outperformed the average North American fund over both 10 and 15-year horizons.
Two caveats apply: Invest Europe is the trade association for the European private equity industry and has an institutional interest in European private capital appearing competitive; and the report acknowledges that Cambridge Associates data may carry a modest upward bias, as between 50 and 60% of funds in its benchmarks sit in at least one client portfolio. With those noted, the findings are consistent across seven annual editions of the same report.
Over 10 years, European funds delivered a net IRR of 16.59% against 13.77% for North American peers — a gap that holds in dollar terms at 17.72% versus 14.85%. Over 15 years, Europe still leads: 17.06% against 16.58%. These are average-fund comparisons. They say nothing about individual firms like Sequoia or a16z, whose top-decile returns sit in a category of their own.
The since-inception figure still favours America — 16.39% versus 11.25% for European funds. But that number carries a ghost. European VC came of age during the dotcom bust, deploying capital into the crash without the preceding boom that US funds enjoyed. Strip out that era, and European VC is ahead, and has been for 15 years.
What active funds are returning
The since-inception number is the one most LPs reach for. It is also the least useful for any LP making an allocation decision today. Active European VC funds are running at a 13.48% IRR and a 2.14x TVPI, short for total value to paid-in capital, the cash-on-cash measure of what investors get back relative to what they put in.
80% are currently in profit, with the profitable cohort averaging 2.36x. Even the 19% in loss-making territory are averaging 0.80x, meaning most of the capital has been recovered, even in the worst cases.
The loss-making tail is not a feature of the contemporary European VC industry. It is a historical artefact concentrated in the ICT bust era. On TVPI, European funds delivered 1.99x, compared with 1.95x for North American peers. European funds hold companies longer — 6.46 years to liquidity versus 4.42 years in the US — but when they exit, they return more. Early-stage European funds are quietly delivering higher cash multiples than late-stage: 2.09x versus 1.70x.
Where America still wins
The US retains one genuine edge: the very top of the market. The top quartile of North American VC funds generates a TVPI of 5.68x. European top-quartile funds reach 4.37x. The outlier vehicles remain more likely to sit in a US portfolio. If your mandate is to find the single best fund in the world, America remains the right starting point.
But most LPs build portfolios. Below the top quartile, European and American VC funds perform almost identically. The dispersion of returns in Europe is lower, meaning the gap between a good pick and a bad one is narrower. The advantage extends beyond the venture.
European private markets raised €147 billion in 2025 and across buyout, growth capital, VC, and infrastructure, every segment outperformed its listed equity benchmark that year. European buyout funds return capital in 3.80 years on average, faster than North American peers at 4.51 years.
The narrative has not caught up with the data
The question is no longer whether European private capital is performing. Seven editions of benchmark data now answer that. The question is why European LPs, family offices, and pension funds continue to treat a $15 billion a16z fund as the safe choice while treating a European manager with a 17% IRR over 15 years as a secondary allocation.
Some of it is brand. Some of it is access: the best US funds are rationed, and pursuing them signals sophistication to investment committees even when the return data no longer support the premium. Some of it is inertia dressed up as due diligence.
For European institutional investors, including pension funds, insurers, and sovereign wealth funds with a mandate to fund returns for European citizens, the Invest Europe report is clear: European private capital exposure cannot be replaced by commitments to other regions or replicated by listed equity strategies.
15 years of outperformance is not a trend. It is a track record. At some point, continuing to ignore it ceases to be a matter of caution and becomes a fiduciary question.
Story based on data: Invest Europe Performance Benchmark Report 2025, Cambridge Associates, as of 31 December 2025. Sample: 288 European VC funds, €54.6 billion total capitalisation.